Billionaire Nelson Peltz bids $1.4 billion to take Wendy’s private
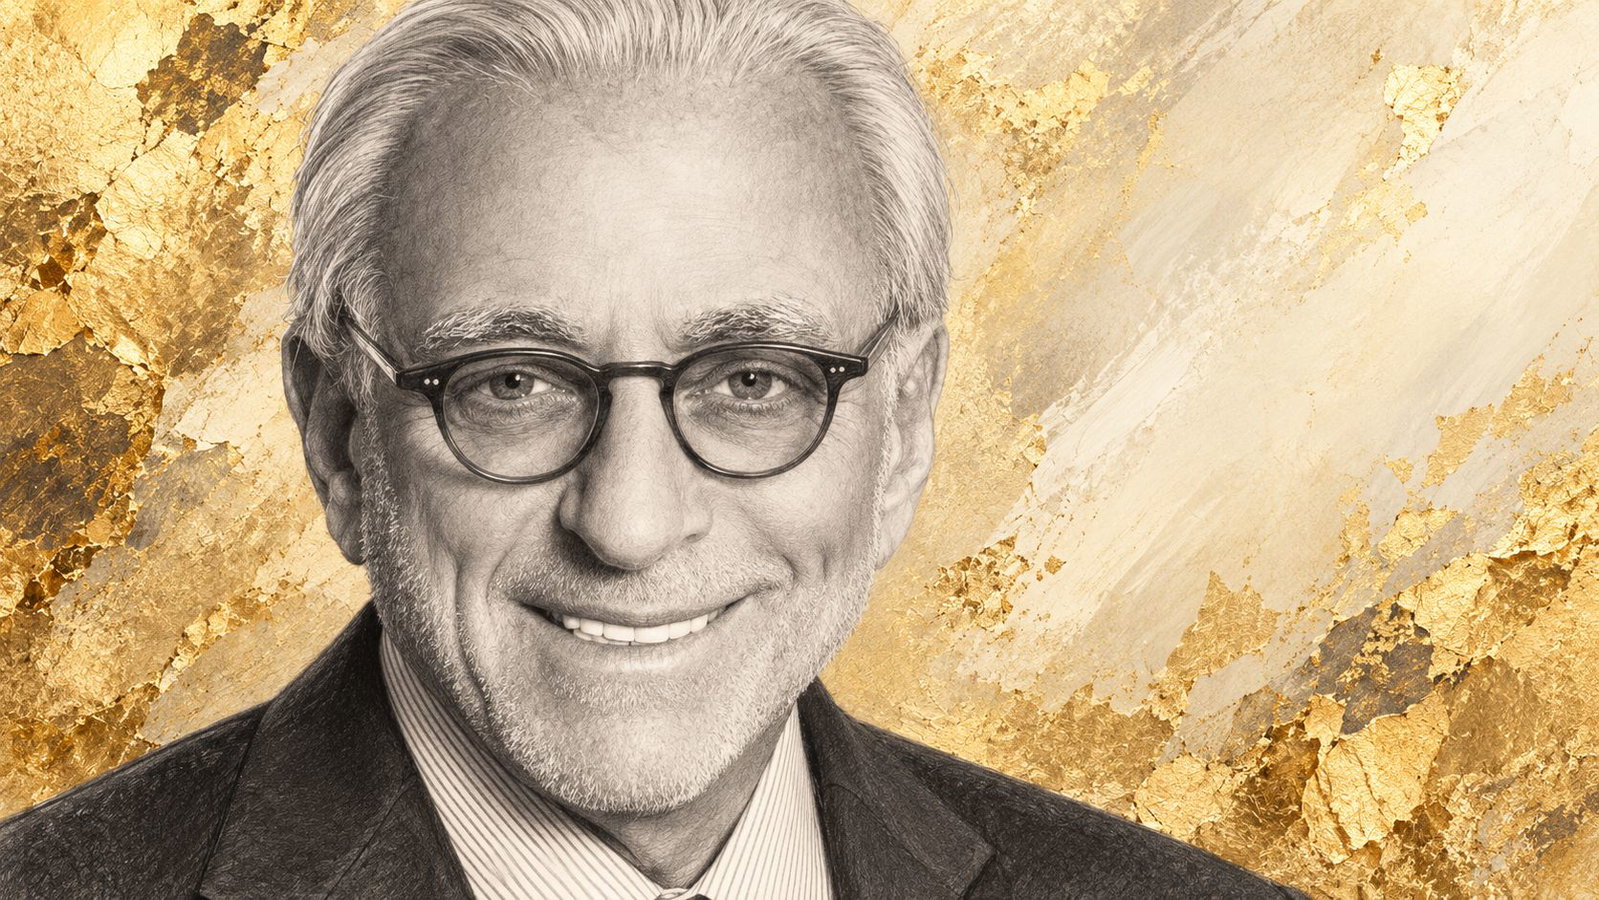
Trian Fund Management, the investment firm run by Nelson Peltz, has offered $7.35 a share in cash for the Wendy’s stock it does not already own, a proposal that values the burger chain at about $1.4 billion. Trian and its affiliates hold about 16.3% of the company. The price is 20% above Wendy’s close of $6.14 on Oct. 27, yet roughly 10% below where the shares started the year.
The bid puts a familiar question to Wendy’s shareholders in an unusually stark form. The company has lost sales for six straight quarters, burned through two chief executives in two years and withdrawn its 2026 forecast. Peltz, who chaired the board for 17 years and remains chairman emeritus, is offering certainty at a discount to January’s price. The independent directors now have to decide whether a turnaround is worth more than that, and whether they can prove it.
What Trian is offering, and with whom
The proposal is non-binding and still needs financing commitments and a definitive agreement. Trian is bidding alongside Flynn Group, one of the largest Wendy’s franchisees in the United States, as well as BlueFive Capital and Sixth Street Partners. Trian co-founder Peter May and Peltz’s son Matthew are also named in the proposal.
In its letter to the board, Trian said Wendy’s faces pressure on consumer spending, rising commodity costs and hard competition among burger chains, and that a turnaround will take years and heavy investment. Private ownership, it argued, would supply “patient, long-duration capital” while the company deals with upcoming debt maturities.
Wendy’s board has formed a committee of directors unaffiliated with Trian and hired Morgan Stanley and Simpson Thacher & Bartlett as advisers. The company said there is no assurance it will pursue this or any other transaction.
The market has given the bid a qualified welcome. Shares rose about 15% on the day it became public, to roughly $7.06. That is below the offer price, a gap that reflects doubts about financing, a possible fight with other shareholders, or both.
The price measured against the debt
A $1.4 billion equity value understates what the buyers would be taking on. On trailing figures, Wendy’s carries about $4.1 billion of total debt and about $340 million of cash, for net debt of roughly $3.7 billion. At $7.35 a share, that gives an enterprise value of about $5.1 billion, or a little over 11 times trailing EBITDA of about $456 million. The cash check is smaller still: buying the roughly 84% of shares Trian does not own would cost about $1.17 billion.
Most of the debt sits in a whole-business securitization of about $2.8 billion, notes backed by franchise royalties and carrying a blended coupon below 4%, with repayment dates beginning in 2028. Structures of this kind typically treat a change of control as an event requiring noteholder consent or refinancing. If the buyers have to refinance at current rates, the interest bill rises, and that higher cost comes out of the cash flow a private owner would rely on to fund the turnaround. Trian has not disclosed its financing plan, and how it treats the securitized notes is the single largest unknown in the bid.
A brand losing ground
Wendy’s operational record explains why Trian sees an opening. U.S. same-restaurant sales have fallen for six consecutive quarters, including a 7.9% drop in the second quarter, when traffic fell 12.5%. Second-quarter adjusted earnings per share fell 38% to 18 cents. The company halved its quarterly dividend to 7 cents and closed 289 U.S. restaurants in the first half of the year. Its share of U.S. burger-chain sales slipped to 10.4% last year from 11.5% in 2019.
The franchise system shows the strain. Meritage Hospitality Group, which ran 314 Wendy’s outlets, filed for bankruptcy in September after the company moved to end its franchise agreement. Leadership has been unsettled too. Todd Penegor left in early 2024; his successor, Kirk Tanner, departed for Hershey after about 18 months, and Wendy’s went roughly nine months without a permanent chief executive before hiring Bob Wright.
Against that record, the Flynn Group’s place in the bidding group matters. A large franchisee inside the ownership would align the company with the operators who carry most of the system’s capital spending, at least on paper. It also raises a governance question for other franchisees, who may wonder whether the new owner’s largest operator would get favorable treatment on remodel requirements or fees.
The shareholder vote and the opposition
Blackwells Capital, a Wendy’s shareholder, has said the proposal “dramatically undervalues Wendy’s” and should be rejected. Its sharper point concerns arithmetic. With Trian already holding about 16.3%, a simple majority could be reached with support from only about 40% of the remaining shares. Trian’s proposal does not, on present information, include a condition requiring approval by a majority of the shares it does not control. Whether the special committee insists on one will say a great deal about how it views its job.
Trian has tried this before. It explored a take-private in 2022 and abandoned it in January 2023, citing improved momentum. Peltz’s association with the company runs back to 2008, when Triarc, the Arby’s owner he controlled, merged with Wendy’s. That history cuts both ways. Few investors know the business better, and few would face closer scrutiny over whether an insider is buying at a cyclical low.
Why this matters for business leaders
For boards, the Wendy’s bid is a case study in insider take-privates at depressed prices. A former chairman with a 16% stake has better information than public shareholders and a strong position in any vote. Independent committees in that situation protect themselves, and the company, by testing the market for other buyers, publishing a credible standalone plan and requiring approval from unaffiliated holders. Skipping those steps invites litigation and activist opposition.
For investors and lenders in franchised restaurant companies, the bid shows the limits of the asset-light model when traffic falls. Royalty-backed securitizations fund cheaply in good years. When same-store sales decline, the same structure limits flexibility, and a change of ownership can force refinancing at worse terms. The equity value in the headline is only the visible part of the transaction.
Executive takeaways
Trian has offered $7.35 a share, about $1.4 billion, for a chain that has lost sales for six quarters and whose shares had fallen 26% this year before the bid. Including roughly $3.7 billion of net debt, the deal values Wendy’s at about $5.1 billion, and the treatment of its low-cost securitized debt will shape the bid’s economics. Directors facing a similar insider proposal should test the market and require approval from unaffiliated shareholders before they negotiate price.
Wendy’s reports third-quarter results on Nov. 5, the latest evidence the special committee will have of whether Bob Wright’s turnaround is gaining ground. Over the following months, watch whether Trian produces financing commitments and a plan for the securitized notes, and whether another bidder appears. If none does, the vote will turn on whether unaffiliated shareholders believe a recovery will lift the shares above $7.35 sooner than Trian expects.
Have you read?
Kessington Adebutu Funds ₦800 Million Lagos Security Trust Headquarters.
Vincent Bolloré’s Canal+ Reports €6.4 Billion Nine-Month Revenue.
Mike Ashley’s Frasers Takes Control of Hugo Boss.
Robin Zeng’s Fortune Falls $14.9 Billion Amid CATL Slowdown.
Carl Icahn Sells Former Trump Plaza Site for $6.6 Million.

Follow CEOWORLD Magazine on: Google News, LinkedIn, X (Twitter), and Facebook.
Note: The views expressed are those of the authors and do not necessarily reflect those of CEOWORLD Magazine, its Editorial Board, or management. Content is provided "as is," may contain monetized links, and is not professional advice. See our Ethics & Guidelines for details. Reproduction requires prior written permission.
Contact info@ceoworld.biz for inquiries or media requests.